Retail & office
Single-tenant and multi-tenant retail, strip centres, professional and medical office, and mixed-use buildings.
Commercial property
Financing for retail, office, light industrial, mixed-use and larger multifamily property — acquisition, bridge, construction and owner-occupied. Underwritten on the asset, its tenants and its cash flow.
What we finance
Single-tenant and multi-tenant retail, strip centres, professional and medical office, and mixed-use buildings.
Warehouse, flex space and distribution property.
Apartment buildings above the residential threshold, held for income or being repositioned.
Buying the premises your own business operates from, instead of continuing to pay rent.
Short-term financing through lease-up, repositioning or a maturing loan, until permanent financing fits.
Site acquisition and the horizontal work needed before vertical construction can start.
Programs
Prepare early
Lease length, renewal and termination rights, escalations, who pays which operating costs, and the financial strength of each tenant are all examined. Have complete, signed leases ready — gaps here are the most common cause of delay.
A current rent roll and three years of operating statements where available. For owner-occupied deals, business financial statements and tax returns.
Appraisal, environmental, property condition, survey and title. Budget the cost and the calendar from the start rather than discovering them mid-process.
Many commercial loans do not fully amortise. Know whether yours has a balloon and when it falls, and plan the refinance or sale well ahead of that date.
Vector Interactive Group has provided commercial development services since 2014. If you own commercial property you want to develop, or you are a national, regional or local company planning to expand in Northeast Florida, we can support the project on the delivery side as well as the capital side.
They are separate engagements — taking one does not require taking the other.
Commercial development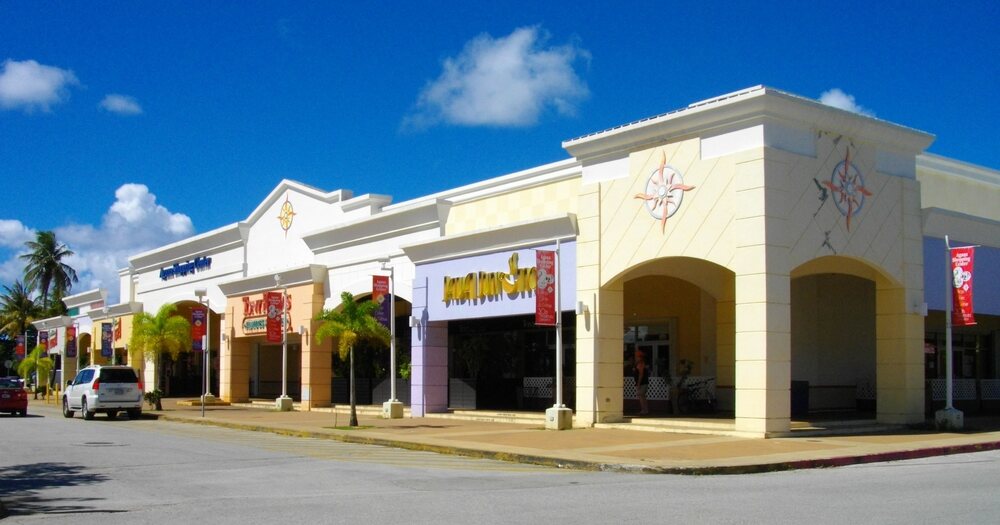
Common questions
Retail, office, light industrial and warehouse, mixed-use, hospitality, special-purpose property, and multifamily buildings of five units or more. Below five units a residential building is generally financed on residential investment programs instead, even when it is held purely for income.
The underwriting is broader and the diligence is heavier. A commercial lender examines the leases and the credit of the tenants behind them, the building's condition and functional suitability, and the depth of the market for that asset type. Third-party reports beyond an appraisal are standard, loan documents are negotiated rather than standardised, and timelines are longer. Start earlier than you would on a residential file.
Owner-occupied commercial financing is a well-established path for businesses that would rather build equity than pay rent. The underwriting focuses on the operating business — its financial statements, tax returns and trading history — alongside the property, because the business is what services the debt. Prepare business financials with the same care you give the property information.
A balloon is the balance remaining when a loan matures before it has fully amortised, and it is a normal feature of commercial lending rather than a trap. It becomes a problem only when it arrives unplanned. Know the date, and start arranging the refinance or sale a long way ahead of it.
Commonly an appraisal, an environmental assessment, a property condition report, a survey and title work, though the exact set depends on the property type, its history and its location. They are typically the borrower's cost and they take real time. We will tell you which your deal needs before you commit to contract deadlines.
It depends on the lender, the asset, the leverage and the strength of the borrowing entity. Some commercial loans are non-recourse, many are fully recourse, and a great many sit in between with guarantees limited to specific circumstances. Treat it as a term to negotiate and understand, not a formality — and raise it early.
Single family, condo, townhouse and small multifamily are handled on our residential side.
Residential loansTell us the property, the plan and the timeline. We will tell you honestly whether we can help and what the realistic next step is.